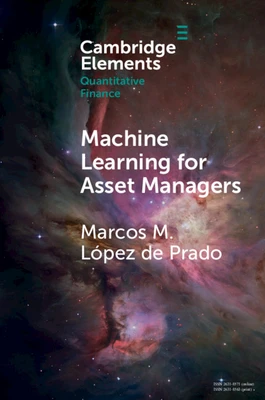
Machine Learning for Asset Managers cover

Machine Learning for Asset Managers

Successful investment strategies are specific implementations of general theories. An investment strategy that lacks a theoretical justification is likely to be false. Hence, an asset manager should concentrate her efforts on developing a theory rather than on backtesting potential trading rules. The purpose of this Element is to introduce machine learning (ML) tools that can help asset managers discover economic and financial theories. ML is not a black box, and it does not necessarily overfit. ML tools complement rather than replace the classical statistical methods. Some of ML's strengths include (1) a focus on out-of-sample predictability over variance adjudication; (2) the use of computational methods to avoid relying on (potentially unrealistic) assumptions; (3) the ability to "learn" complex specifications, including nonlinear, hierarchical, and noncontinuous interaction effects in a high-dimensional space; and (4) the ability to disentangle the variable search from the specification search, robust to multicollinearity and other substitution effects.

Pages 152 Pages
Published April 30, 2020
Language English
ISBN 9781108792899
ASIN 1108792898
7 Views
1 Readers
User Stats
  • 0 Reading
  • 1 Plan to read
  • 0 Completed
  • 0 Paused
  • 0 Dropped

Readers shows the total users who added this book. User stats show which reading list type they currently use.

Reviews (0)
0.0
0 ratings · 0 reviews
5 ★ (4.5 to 5 stars)
0
4 ★ (3.5 to 4 stars)
0
3 ★ (2.5 to 3 stars)
0
2 ★ (1.5 to 2 stars)
0
1 ★ (0.5 to 1 star)
0
No reviews yet. Be the first!